All Categories
Featured
Key Tips for Selecting Burial Insurance
Table of Contents
Instead you address a set of health questions, and the carrier checks prescription records. That unlocks to individuals who would deal with a completely underwritten policy candidates in their seventies, individuals managing diabetes or heart disease, individuals who have had cancer. It is typically the only life cover readily available to them, and it is really helpful for that factor.
Final cost insurance coverage costs more per thousand dollars of cover than a completely underwritten policy would for a healthy candidate. If you are in health and want a larger advantage, ask us to quote a standard policy along with it before you choose. This is the single essential thing to understand, and the important things usually glossed over.
Medicare in Huntington BeachThis is what you desire, and a lot of reasonably healthy applicants get approved for it. The policy pays a reduced percentage of the benefit if death happens in the very first two or 3 years, rising to the full amount afterwards. No health questions at all, however if death takes place within the first two years the policy normally returns only the premiums paid plus interest not the survivor benefit.
Medicare in Huntington BeachAdvertising for last expenditure insurance coverage seldom identifies in between these. A household expecting a payment and getting a refund of premiums instead is a bad afternoon that a single concern at the application stage would have avoided. Ask which type you are being offered and get the response in writing. Term and entire life over one lifetimeIt fits individuals whose staying insurance coverage need is small and particular.
How Indexed Universal Life Benefits Enhance Retirement
It suits individuals who can not pass full underwriting but can respond to a short health survey honestly and get approved for a level advantage. And it suits individuals who want the certainty of permanent cover at a premium that fits a set retirement earnings. It does not match someone still changing an earnings.
A final expense insurance plan pays cash to the recipient you name. It is not tied to any specific funeral home and it does not need to be spent on a funeral service at all. That versatility is typically a benefit, however it puts weight on who you name. Name an individual who will in fact be present and arranged in the days after your death, and inform them the policy exists.
Some individuals choose to assign a part of the advantage straight to a funeral company so the plans are paid without the household fronting cash. That is a separate plan from a pre-need or pre-paid funeral service agreement, which is managed in a different way and is not insurance in the same sense. If you already hold one, inform us before purchasing, so you do not pay twice for the same thing.
Validate which you have. Rates for the very same health profile differ materially in between carriers, and the difference is not visible from one quote. Work out the actual expected cost in your location, include a margin, and buy that. Paying premiums for decades on an advantage twice the size of the requirement is money leaving the home on a monthly basis.
2026 Life Insurance Strategies for Family Security
Keep the policy number where the family will find it. Rate the real requirement where you live, since funeral costs differ widely by area and by what you select.
You are entitled to buy only the items you desire instead of a package. Sound 2 or 3 service providers near you and request for that list. Build up the products your household would realistically choose the service, the casket or cremation, the plot or urn, the transport, the death certificates.
2 things people forget. Cemetery and crematorium charges are typically different from the funeral home's own bill. And if you currently hold a pre-need or pre-paid funeral agreement, part of the cost might already be covered, in which case a smaller last expenditure insurance plan will do. Sizing it in this manner typically produces a lower number than the one people assume, which indicates a lower premium each month for the rest of your life.
Or call. We will tell you which benefit type you qualify for before you use, not after.
Burial insurance coverage, also called funeral insurance, is a useful tool for liked ones paying for a left member of the family or pal's funeral service, funeral, headstone, urn, and other final expenditures. It is basically a life insurance coverage policy, however with a much smaller benefit quantity than conventional life insurance. It's generally acquired to cover final arrangements, however can also be used to pay the deceased's financial obligations, including medical costs, charge card expenses, mortgage, and individual loans.

Table of Contents
Latest Posts
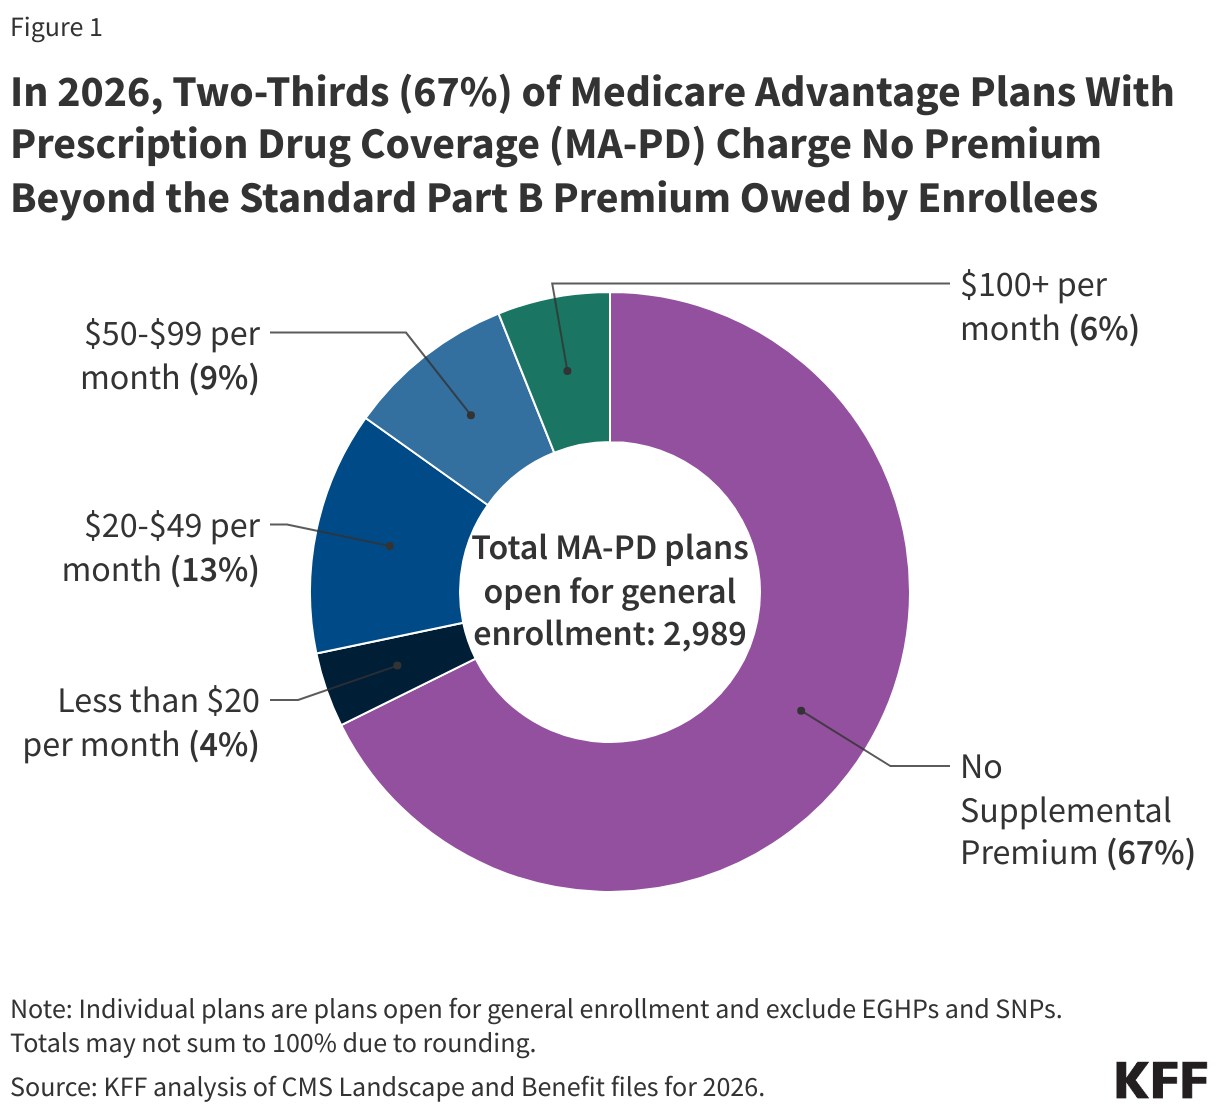
Reviewing Medicare Supplement Plans for Maximum Coverage

How Final Expense Insurance Provides Peace of Mind for Families
The Tax Benefits of Investing in Health & Life Insurance
Latest Posts
Reviewing Medicare Supplement Plans for Maximum Coverage
How Final Expense Insurance Provides Peace of Mind for Families
The Tax Benefits of Investing in Health & Life Insurance