All Categories
Featured

Evaluating Term vs Whole Life Insurance
That versatility can be substantial if your income changes from year to year, or you go through a huge life event (such as divorce or momentary work leave) and still wish to keep your policy in force. It also suggests you'll need to pay closer attention to your policy over time.
This table highlights the greatest distinctions: Both entire life insurance and indexed universal life provide you with permanent coverage that builds cash value, however how that cash value grows is quite various. Whole life insurance coverage generally has actually ensured development at a fixed rate, while IUL has the potential for greater returns due to the fact that its money value is connected to a market index.
Term life insurance coverage is generally the most cost effective and simplest type of life insurance coverage to get. It does not build money worth, but you get a guaranteed death benefit for a set time period, often at a fraction of the expense of an IUL policy. You can think about a variable universal life insurance coverage policy as one action above an IUL policy in terms of danger and reward.

This suggests you'll have higher growth capacity however also the possibility of investment losses. Like any financial product, indexed universal life insurance coverage has benefits and compromises. If your main objective is simply replacing your earnings for your family, a term life insurance policy is generally easier and far less costly.
Cheap Individual Medical Quotes for 2026
Typical expenses may include:, which generally increases as you age for handling the policy subtracted from your payments if you include features like long-term care or persistent health problem benefits if you cancel the policy during its early years Before you purchase an indexed universal life policy, the insurer will normally provide an illustration demonstrating how your policy could carry out over time.

Latest Posts
Life Insurance Benefits for Veterans
Evaluating Term vs Whole Life Insurance

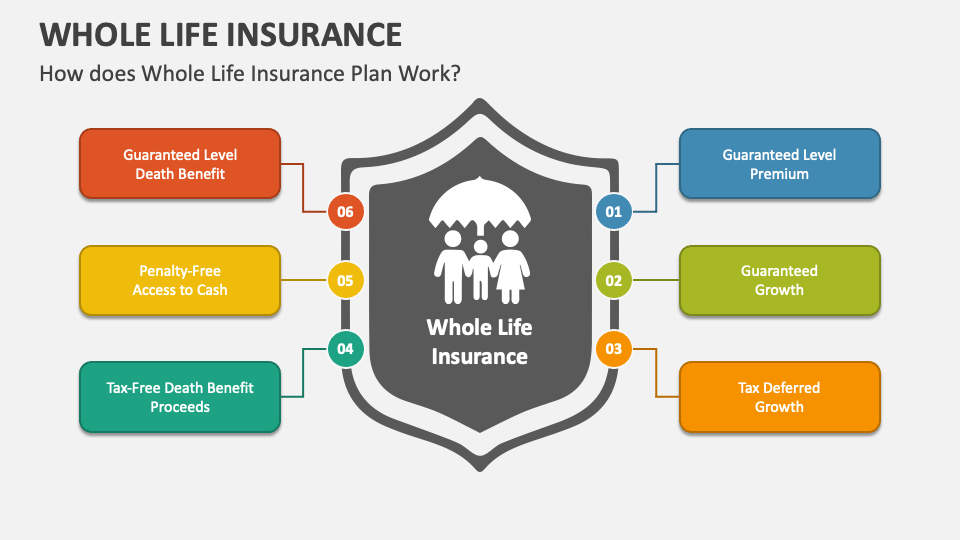
Securing Long-Term Security with Whole Life Insurance